According to The Department of Health and Human Services, over half of people over 65 will experience a long term care event. How long that care lasts and how much it costs varies enormously from person to person.
To pay for that care, three public options exist, but none offer a complete answer. At the federal level, Medicare does not cover long term care. Medicaid does, but only after you’ve spent down enough assets to qualify. At the state level, Washington State launched its WA Cares Fund, the first state program of its kind, with a lifetime maximum benefit of $36,500. A handful of other states are at various stages of examining their own programs.
That leaves self-funding as one of the most common approaches. After working with clients for over 50 years, we understand the appeal. You keep control of your money and avoid insurance premiums. For some, this works well, but for others, the reality turns out to be more complicated. If you’re considering self-funding future long term care, you should know the answers to the following four questions.
How much will it cost?
Genworth’s Cost of Care tool helps estimate costs by state. This will give you an idea of monthly costs, depending on where you live.
How long you’ll need care is hard to predict. Modern medicine keeps people alive longer, but not always healthier. An average can get you started, but it’s not a strategy. The national average for a long term care event is approximately 3 years. Our clients’ claims have averaged 4.2 years, with some lasting well over a decade.
Where will you get the money to pay?
Most people who self-fund draw on the same assets funding their retirement. Which accounts will you tap into first? Cash savings? Taxable? Pre-tax? If you use pre-tax accounts, remember that withdrawals trigger income tax, which accelerates asset depletion.
One variable that’s easy to overlook is market conditions when you tap accounts. If the market is down when you liquidate a holding, you lose the chance to ride the market back up.
Is your family on board?
Self-funding often means a spouse or adult children take on some of the caregiving. Are they prepared? If you’re not able to make decisions for yourself, who will make them for you? Are they clear on what you want? Finally, if you’ve earmarked assets for your heirs, are they aware they might receive less than you intended? Have these discussions ahead of time.
Does Long Term Care Insurance have a place even when self-funding?
Most of our clients combine self-funding with Long Term Care Insurance (LTCI). Like you, they can’t predict for certain if they’ll have a long term care event or how long it will last. They combine both options for peace of mind. LTCI acts as a backstop against a lengthy or more costly claim. It signals the level of care they want and relieves the family of the expectation that they’ll have to provide it. And for legacy minded clients, it helps fund future care while protecting the assets they intend to pass on.
LTCI isn’t right for everyone. But for those self-funding, it’s worth understanding what role it might play.
A final thought
The earlier you think through costs, funding sources, family roles, and contingencies, the more options you’ll have. Whatever approach you take, the goal is to make sure that if care is needed, you have the funds and family support to handle it. If you have questions about funding your own long term care, please contact us.
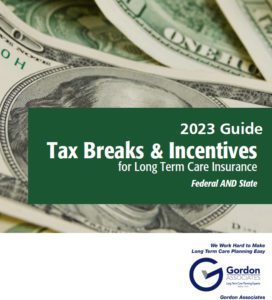 To help determine if long-term care (LTC) insurance is right for you, we are offering a FREE informational guide. This is a comprehensive booklet that will answer many of your questions about tax breaks and incentives for LTCI for federal and state taxes.
 To help determine if long-term care (LTC) insurance is right for you, we are offering a FREE informational guide. This is a comprehensive booklet that will answer many of your questions about LTC and assist you with your health care planning.